All Categories
Featured
The UK is especially exposed provided its dependence on gas for electrical power pricing, which is why the International Monetary Fund (IMF) has modified its UK inflation and development projections more dramatically than any other developed economy. Inflation briefly dipped below 3% for the very first time because early 2025, however the reprieve will be brief.
A weaker labour market and softer need should prevent a repeat of 2022's double-digit spike, restricting second-round impacts. Our base case is inflation balancing 3.1% in 2026, peaking around 3.5%, before easing to 2.5% in 2027, though threats loom large if the Strait of Hormuz stays closed. The UK labour market was currently softening before the newest energy shock, with unemployment rising to 5.0% and vacancies at their most affordable because the pandemic.
Mastering UK Mid-Market Global Growth for 2026Companies are not yet shedding staff, however hesitation to hire is widening the space in between task development and population development. Higher energy expenses will compound the pressure, and we expect joblessness to peak at 5.3% by year end. With wage growth slowing to around 3.75% and inflation heading towards 3.5%, genuine pay looks set to be stagnant another hard year for living standards.
Mastering UK Mid-Market Global Growth for 2026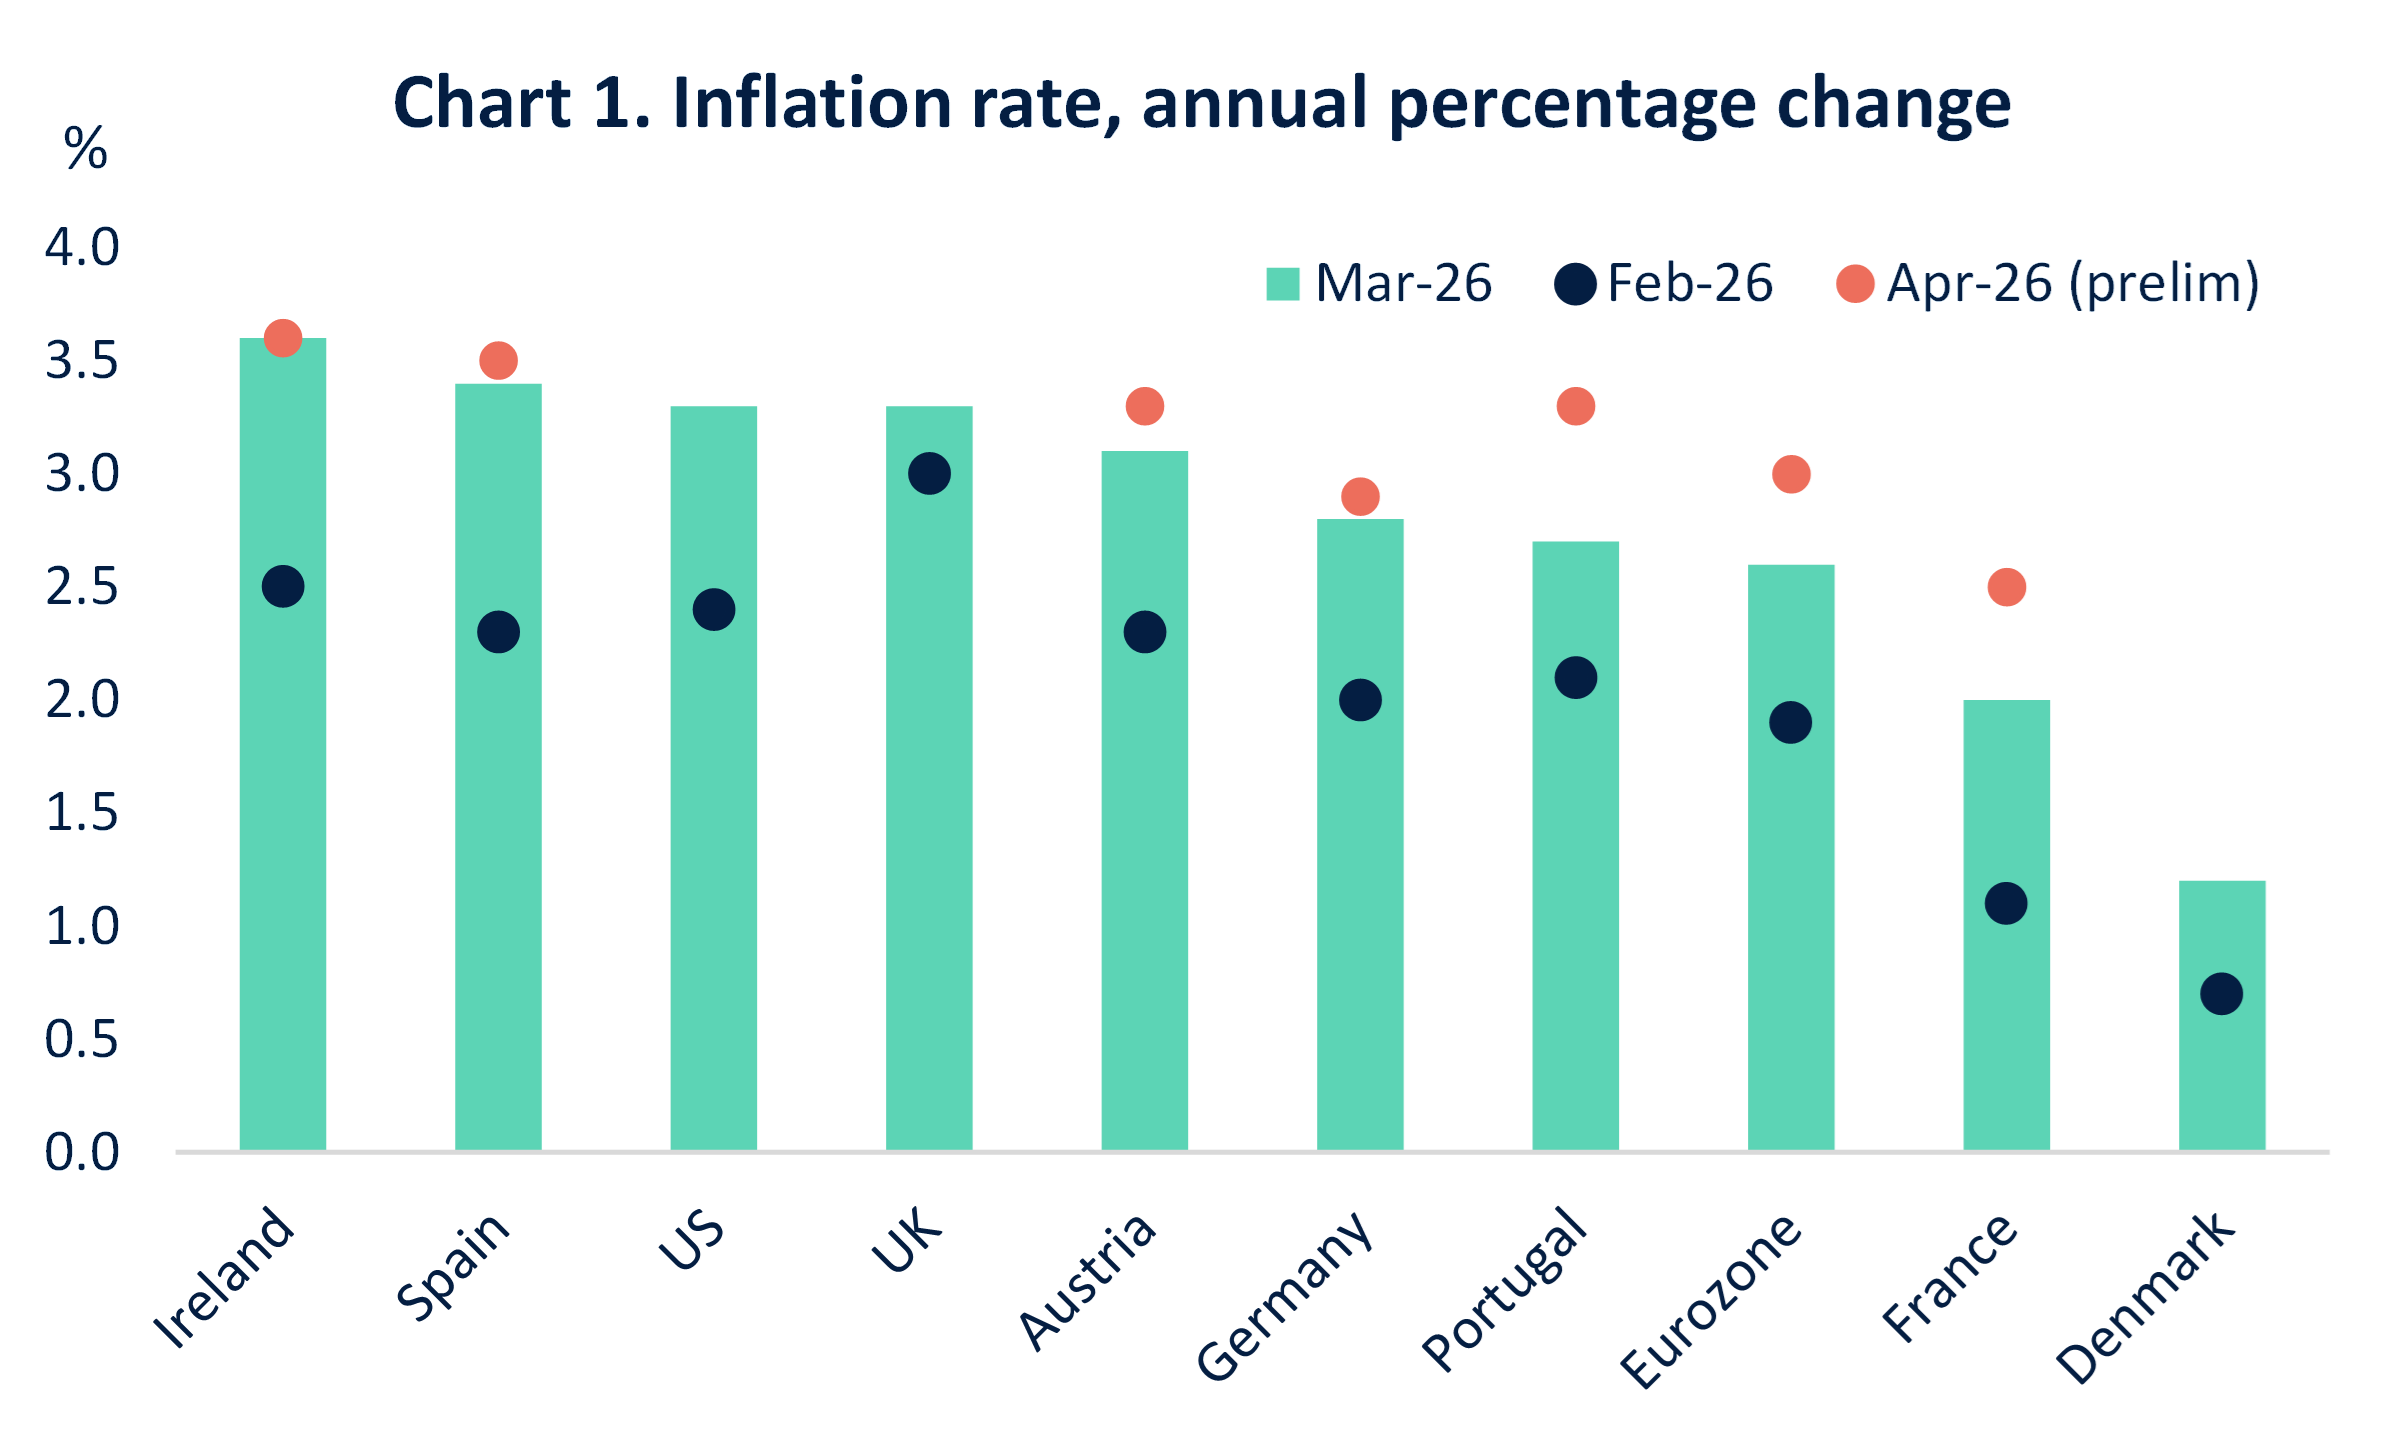
3 elements limit the case for hikes: the energy shock is smaller than in 2022, rates are currently at a limiting level, and a weaker economy decreases the danger of second-round inflation effects. That stated, rate increases can not be eliminated if energy prices surge further. Gilt yields are likely to stay elevated regardless, driven by the UK's inflation level of sensitivity and political uncertainty around a prospective change of Prime Minister, keeping loaning expenses high throughout the economy even if the policy rate remain on hold.

Latest Posts
How AI Drives British Enterprise Success
Why Global Trade Dynamics Matter for British Firms
Navigating the 2026 British Economic Landscape